0% read
Last updated:
Frankencoin
Frankencoin is a decentralized, collateralized stablecoin protocol designed to keep the value of its Swiss franc-denominated token in line with the Swiss franc (CHF) through over-collateralized positions, governance mechanisms, and market-based incentives. The system uses Frankencoin (ZCHF) as its Swiss franc-denominated stablecoin and Frankencoin Shares (FCS) as its on-chain equity and governance token, with FCS providing governance rights and exposure to the protocol’s reserve pool.[1] Frankencoin Shares (FCS) is backed by the ZCHF reserve pool and is tradable on decentralized exchanges.[8]
Compare Cryptoassets
Select an asset to compare its price and other stats against Frankencoin.
Overview
Frankencoin is a decentralized, overcollateralized stablecoin protocol built on Ethereum that issues Frankencoin (ZCHF), a stablecoin designed to track the value of the Swiss franc, and uses Frankencoin Shares (FCS) as its single equity and governance token representing a share of the protocol’s ZCHF reserve pool. FCS provides veto-based governance rights over collateral types and minting mechanisms, and earlier governance tokens, Frankencoin Pool Shares (FPS), were migrated 1:1 into FCS when the new token was introduced.[8][6] Unlike many collateralized stablecoins, Frankencoin does not rely on external price oracles to trigger liquidations. Instead, it uses an economic model based on overcollateralization, governance, and market incentives to maintain price stability, with liquidations occurring over longer timeframes. The protocol is governed through a veto-based system in which FCS holders can approve or reject new collateral types and minting mechanisms, while also assuming the financial risks and rewards associated with the system.
The protocol supports several primary functions, including payments, borrowing, and Swiss franc-denominated digital assets. Users can mint ZCHF by depositing approved collateral into on-chain borrowing positions, similar to vaults used in other decentralized lending protocols, with borrowing costs charged upfront and reserves maintained to support liquidation events. The protocol consists of a series of Ethereum smart contracts that manage token issuance, collateralized debt positions, governance, and collateral approval. Its architecture allows additional minting contracts to be introduced through governance, enabling the system to support new collateral types and issuance mechanisms over time.[2]
History
Frankencoin was developed from research by Luzius Meisser at the University of Zurich and is based on the concept of a Continuous Capital Corporation, an autonomous financial system designed to manage capital through smart contracts, governance mechanisms, and market incentives. The protocol’s design explores the economic principles behind collateralized stablecoins, including collateral risk, auction-based liquidations, governance structures, and the incentives required to maintain price stability. Unlike fiat-backed stablecoins that depend on centralized issuers or traditional banking systems, and algorithmic stablecoins that rely primarily on market-based mechanisms, Frankencoin uses a combination of overcollateralization, equity-backed governance, veto controls, and oracle-free collateral valuation. The system’s model places decision-making responsibility with participants who have financial exposure to the protocol, aligning incentives between governance participants, collateral providers, and stablecoin users.[1]
Features
Savings Module
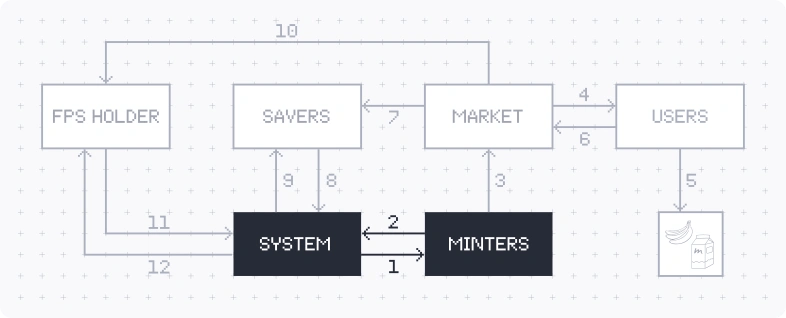
The Frankencoin Savings Module is an Ethereum-based smart contract that enables users to deposit Frankencoin (ZCHF) and earn a governance-defined savings yield while retaining full ownership of their assets. Unlike traditional lending protocols, deposited ZCHF is not loaned to other users or used as collateral to support the protocol, remaining fully segregated and available for withdrawal at any time. Interest is funded by the protocol's equity pool, begins accruing after a three-day waiting period intended to discourage short-term transactional deposits, and is calculated as simple interest on the principal balance rather than compounded. The savings and borrowing rates are determined independently through Frankencoin's governance process. The module also includes an optional referral mechanism that allows wallets, decentralized applications, and other integrators to receive a configurable share of the interest earned by referred users, providing an incentive for third-party integrations while preserving the protocol's decentralized savings infrastructure.[4]
Collateralized Minting
Frankencoin uses a collateralized minting system that allows users to create new ZCHF by locking approved collateral into on-chain borrowing positions. Each position is owned by a single user, who can deposit collateral and mint ZCHF up to a predefined limit based on a liquidation price rather than an externally supplied market price. Unlike many decentralized stablecoin protocols, Frankencoin does not rely on price oracles. Instead, it uses a challenge-and-auction mechanism in which any participant can dispute a position they believe to be undercollateralized. If challenged, the collateral is auctioned to establish a market price and determine whether the position remains sufficiently collateralized. Users can either propose entirely new collateral types, subject to governance review, proposal fees, and defined financial parameters, or immediately mint ZCHF by cloning an existing approved collateral position, allowing faster access to borrowing under standardized terms.
Once a position has been created, its owner can adjust the collateral amount, outstanding debt, and liquidation price, while minting fees and reserve requirements are applied upfront to help protect the protocol against losses. Repaying borrowed ZCHF releases the associated collateral, and reserve balances may be used to offset part of the repayment or absorb losses during liquidations. The protocol's auction design is intended to reduce opportunities for price manipulation by separating the incentives of position owners and challengers, eliminating the need for external price feeds while ensuring collateral values are determined through open market bidding. If an auction concludes below a position's liquidation threshold, the collateral is liquidated, reserves are applied toward repayment, challengers receive predefined rewards, and any remaining gains or losses are absorbed by the protocol's equity pool, making governance participants responsible for the system's residual risk.[5]
Tokens
ZCHF
Frankencoin (ZCHF) is a collateralized stablecoin designed to track the value of the Swiss franc through economic incentives rather than a direct fiat-backed reserve or external price oracle. The system requires over-collateralization, meaning each Frankencoin in circulation must be backed by collateral assets with at least equivalent value. Instead of relying on oracle-driven liquidations, Frankencoin uses market-based mechanisms that allow greater flexibility in accepted collateral types while reducing dependence on external data sources, although this results in slower liquidation processes. Frankencoin Shares (FCS) holders influence the system’s long-term stability by adjusting economic parameters such as minting costs, creating incentives to maintain alignment between ZCHF and the Swiss franc while protecting the value of the broader protocol.[2][3] Users can also access a 1:1 bridge between ZCHF and the CHFAU asset, enabling redemption of on-chain ZCHF into Swiss franc-denominated bank money through intermediating infrastructure.[2]
FCS
Frankencoin Shares (FCS) are the equity and governance token of the Frankencoin protocol, representing a claim on the reserve pool that accumulates fees and interest from ZCHF minting. Users can add reserve capital to the protocol to receive newly created FCS, while redemptions reduce the share supply, so that FCS supply expands only when new capital enters the reserve pool and contracts when capital exits. The value of FCS reflects the financial position of the protocol, increasing as the system accumulates income from borrowing fees and successful liquidations, and decreasing when reserves absorb losses, giving holders exposure to both the upside and downside of protocol performance.[8]
FCS grants time-weighted governance rights in which voting power grows with both token holdings and holding duration, rewarding long-term participation. Holders can veto proposed new minters and collateral positions with a relatively small share of total voting power, with around 1% of votes being sufficient to block changes under the protocol’s veto rules.[8] The protocol uses a predefined capital valuation model in which the market value of FCS is tied to the amount of equity held in the reserve pool rather than determined solely by secondary-market trading, allowing users to mint or redeem shares against the pool’s net asset value. When FCS was introduced, the earlier governance token, Frankencoin Pool Shares (FPS), was migrated 1:1 into FCS, preserving prior holders’ proportional exposure and governance rights without altering the underlying economic structure of the reserve pool.[6]
Governance
Frankencoin uses a veto-based governance model designed to balance decentralization with operational efficiency. Rather than relying on lengthy token-weighted voting processes, governance allows participants to submit proposals that can be enacted if no qualified Frankencoin Shares (FCS) holders veto them during a defined review period. Proposals typically require a fee and can include changes such as introducing new collateral types or minting modules. The system’s smart contracts are immutable after deployment, but modular extensions can be added through governance, allowing new functionality such as collateralized minting, savings mechanisms, and cross-chain integrations without altering the core contracts.
Governance power is determined through accumulated FCS voting rights, which increase based on both token ownership and holding duration, rewarding long-term participation while limiting short-term manipulation.[8] Holders with around 1% of voting power can block proposals, with delegation mechanisms allowing participants to combine voting power across addresses. The governance model extends across supported blockchains by allowing mainnet voting rights to be verified on other networks. By relying on economic incentives, long-term capital commitment, and targeted veto authority rather than frequent votes, Frankencoin aims to maintain decentralized oversight while reducing governance complexity.[7]
Partnerships
See something wrong?
Official Website:
Social Profiles:
Founders: