0% read
Last updated:
Ramses
Ramses is multichain decentralized exchange and liquidity infrastructure that began on Arbitrum. Its current HyperEVM system uses RAM and xRAM to direct weekly liquidity emissions.[22][21][23]
Overview
The earlier Ramses model used the ve(3,3) design associated with Andre Cronje. In that model, swap fees were allocated based on pools users voted to receive token emissions, rather than distributing a portion of all protocol fees to token-locking users like other exchanges. Current governance and fee arrangements are deployment-specific.[1][19]
Ramses has described a mechanism known as "bribing," allowing users or projects to allocate token emissions to specific pools. This assists in providing initial liquidity support for projects in their early stages.[2]
Partnerships
Partners previously named in Ramses documentation include Liquity, The Ennead, Frax Finance, Liquid Driver, fBOMB, Shrapnel DAO, DEUS, Tarot, YFX, Angle, EI-Ramses, Oath, Inverse Finance, QiDAO, xCAD, GND Protocol, GMD Protocol, Gains Network, Firebird, Jarvis Network, Radiant Capital, DAOMaker, Beefy, Yearn, Granary, Vela Exchange, UNIDEX, Root, Ankr Network, Alchemix, Olympus DAO, Gamma, BLOTR Protocol, Arken Finance, SYMM I / O, Gravita Protocol, Muon, Ethos Reserve, PaintSwap, Swell Network, DefiEdge, Ichi, Davos Protocol, 1inch, Paraswap, Odos, Kyberswap, LayerZero, Axelar, Savvy, and others.[3]
History
Ramses launched on Arbitrum in March 2023 as an automated market maker designed to improve capital efficiency and align incentives across decentralized finance.[22]
The protocol expanded to HyperEVM in 2025, where it functions as a liquidity layer in the Hyperliquid ecosystem. It later developed Ramses X as multichain infrastructure combining LayerZero OFT token connectivity with chain-specific execution and liquidity. The protocol’s product and token architecture varies by deployment: the earlier Arbitrum veRAM model remains part of its history, while HyperEVM uses the current x(3,3) system.[22][19][20]
Functionalities
Swaps
Swap prices and slippage depend on the total value locked in liquidity pairs and on whether arbitrage activity has brought a pool into line with its market rate. Ramses documents two types of liquidity pools with different swap curves; see Technology and Architecture for their mechanics.[4]
Voting
The veRAM NFT serves to allocate emissions to LP token pairs through a voting process. Emissions are distributed based on the proportion of votes in a given epoch.[5]
Bribing
Two types of bribes are offered within Ramses: [6]
- Vote Bribes: Users and protocols can offer rewards to voters. This encourages voters to choose specific token pairs for emissions. In return for their votes, users offering the reward gets a share of the rewards.[6]
- Gauge Bribes: Apart from emissions, tokens can be provided as bribes directly to LP (liquidity provider) stakers. This encourages the expansion of liquidity in specific token pairs, particularly favoring protocols aiming to efficiently initiate liquidity within the RAMSES AMM. [6]
Vesting (veNFT Management)
In order to manage their veRAM, users can create locks and manage them by increasing lock amount, increasing lock length and merging veRAM positions. [7]
LP Staking
In the earlier RAMSES model, LP providers did not receive swap fees, as fees were directed to veRAM holders. Staking gauges were used to encourage users to supply LP tokens, allowing them to earn competitive APRs. The higher the number of votes allocated to a pair, the greater the amount of RAM distributed to the gauge in the subsequent epoch. A user's gauge boost affected the rate of rewards for each LP position. Fee rules and governance now vary by deployment; under the current default configuration, gauged pools direct 100% of swap fees to voters, while ungauged pools split fees 95% to LPs and 5% to the protocol.[8][21]
Ramses V2
Ramses V2 is based on the ve(3,3) DEX model by incorporating Uniswap V3's concentrated liquidity design alongside the original solid model. This section describes the earlier V2 and concentrated-liquidity design; fee rules and governance are deployment-specific. See Technology and Architecture for the current fee distinction.
Concentrated Liquidity
See Technology and Architecture for the Ramses CL design and its relationship to bribes, emissions, fees, and veRAM voters.
Fee Tier
RAMSES V2 introduces a selection of fee tiers for users to consider when establishing a concentrated liquidity position. These tiers are designed to cater to various types of asset pairs. The options include:[10]
- 0.01%: This tier is well-suited for highly correlated and pegged assets like USDC and USDT, offering advantageous rates.
- 0.05%: Ideal for competitive asset classes such as USDC/WETH, known for generating substantial trading volume.
- 0.3%: Standard for pairs that don't fall into the aforementioned categories.
- 1.0%: Tailored for highly volatile assets, providing sufficient fee generation to offset associated risks.
Additionally, RAMSES V2 provides extra fee tier options:
- 0.005%: Specifically designed for ultra-stable token pairs like USDC-DAI, USDC-USDC.e, and USDC-USDT.
- 0.025%: Customized for competitive blue-chip pairs.
Competitive Farming
Competitive farming is a method of rewarding LP providers based on the productivity and competitiveness of their provided liquidity. In concentrated liquidity models, users have the flexibility to select the specific ranges of liquidity they wish to provide for LP. This allows users to choose from a wide range of tick values, providing a high degree of customization.[11]
RAM Token
RAM is the native token of Ramses. In the earlier Arbitrum-era model, users locked RAM to receive veRAM, which could be used to vote on token-emission allocation and determine which pools received liquidity. User positions were administered through veNFTs. The current HyperEVM x(3,3) system instead uses non-transferable xRAM for governance without fixed-duration locks. Current HyperEVM xRAM is non-transferable voting power used by staked holders to allocate weekly RAM emissions among active gauges; each gauge's vote share determines its share of RAM emissions for the following epoch.[12][9][21]
Token Distribution
The earlier published tokenomics described a terminal supply of 500,000,000 RAM tokens. Its initial distribution consisted of 125,000,000 RAM tokens, with 75,000,000 tokens designated as veRAM. These figures describe that earlier published model, not the current initial distribution.[12]
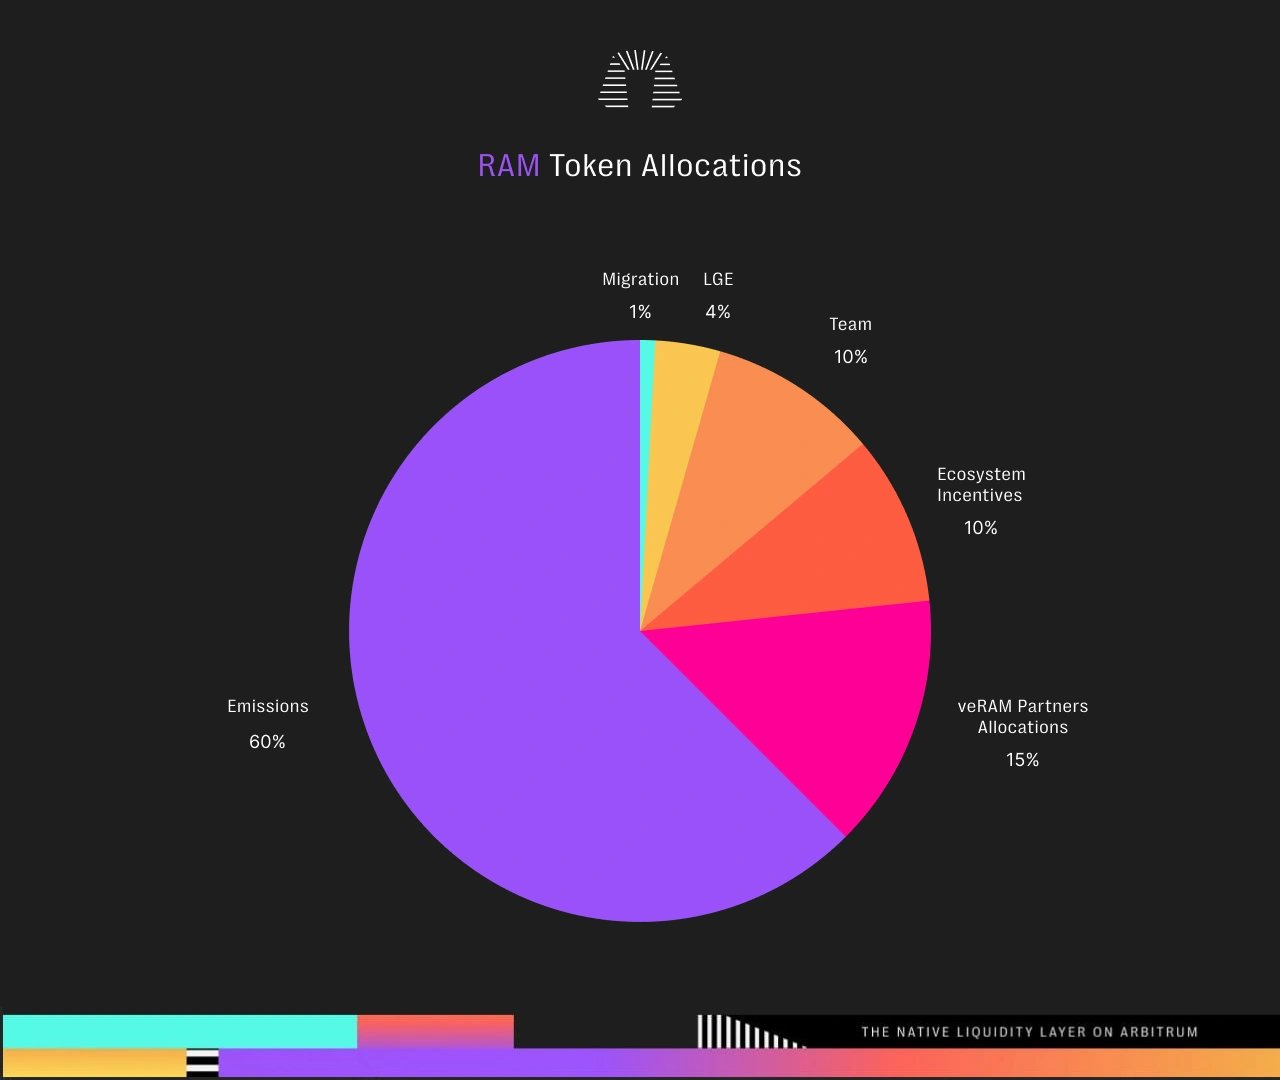
Current published tokenomics give RAM an initial supply of 350,000,000, allocated 45% to the Ramses community (veRAM), 30% to the Hyperliquid community, 23% to the treasury, and 2% to protocol-owned liquidity. Within the 30% Hyperliquid community allocation, 20% was designated for NFT/PiP airdrops and 10% for incentives, including 3% RXP and 7% liquidity and vote incentives. Current documentation gives a maximum outstanding-supply ceiling of 1,000,000,000 RAM, rather than a terminal supply.[23]
Tokenomics
Under the earlier RAMSES (3,3) model, a mechanism mitigated dilution. Initially, veRAM holders received a 50% weekly rebase to help offset dilution resulting from the protocol's emissions schedule. Over time, this percentage increased by 1% with each subsequent epoch (week), until reaching a maximum cap of 75% anti-dilution per epoch.[13]
Under current published tokenomics, emissions are elastic and adjustable. Weekly RAM emissions go to the voter and gauge systems, with no recurring team-emissions allocation. RAM-to-xRAM conversion burns and buybacks are separate supply mechanisms; their existence does not establish that RAM is net deflationary.[23]
veRAM (veNFT)
In the earlier model, veNFTs were specialized ERC-721 tokens that implemented the vested-vote escrow (ve) model and represented a user's underlying position. They offered various functionalities within the RAMSES ecosystem, including the ability to vote on gauge emissions, pools for earning Vote Bribes and Swap Fees, and the capability to transfer or merge NFT positions. Additionally, veNFTs provided protection against dilution through Rebases. These descriptions apply to that earlier model rather than every current Ramses deployment.[14]
The RAMSES Bazaar, based PaintSwap, is the marketplace for veRAM trading and bartering activities.[15]
xoRAM
In the earlier Ramses model, xoRAM was a non-transferable representation of 1 unit of RAM, securely stored within the xoRAM token smart contract. It provided users with different conversion options to both RAM and veRAM, each entailing specific penalties and vesting periods.[16]
Users could obtain xoRAM through vote bribes and emission splits in specific low-impact liquidity pairs. Each gauge could receive a portion of RAM/xoRAM based on the liquidity pair's impact on the DEX's health. Core pair would receive the majority or all of the emissions in liquid RAM. Conversely, pairs with very low trading volume and fee generation would receive a higher percentage of emissions in xoRAM.[17]
Team
The team is composed of the two co-founders DOG and North, front-end developer Mali, smart contract developer Ren, advisors Lafa and Dudesahn, admin King, and community admin Achi.[18]
Multichain Deployments
Ramses DEX deployments are listed on HyperEVM, Arbitrum, Polygon, and Robinhood Chain. HyperEVM is the current home of native RAM and Ramses’ live LayerZero OFT network. Base has live RAM and r33 OFT connectivity but no listed Ramses DEX deployment. Ethereum Mainnet endpoints are configured but inactive and intended to become a hub later. OFT connectivity does not unify liquidity or execution across chains.[19][20]
Swap Curves
Ramses documents two pool types with different swap curves. Volatile, UniV2-style pools use equal dollar value weighting for token pairs and a volatile swap curve. Correlated, Andre-style pools use a stable-swap curve intended to reduce slippage for correlated assets.[4]
Concentrated Liquidity
Ramses CL combines bribes with concentrated liquidity in a custom implementation, where the majority of the platform's revenue was directed towards veRAM voters under the earlier design.[9]
Liquidity providers who provide liquidity in concentrated ranges receive a larger share of emissions or rewards compared to those who provide liquidity in broader price ranges. This model encourages competitive liquidity provisioning and market making that aligns with the highest concentration of utilized liquidity. The veRAM gauge boosting mechanism complements this by rewarding users for actively contributing liquidity to the Ramses system, thereby increasing the utility of veRAM.[9]
Under the earlier CL design, veRAM voters had additional opportunities such as claiming vote bribes and trading fees. Trading fees within CL gauges were distributed among Voters, NFPs, and ecosystem incentives. All of the bribe rewards were allocated to the voters. Fee rules and governance are deployment-specific; the current default distinction is described in Technology and Architecture.[9]
See something wrong?